
Common Financial Recordkeeping Problems That Can Hurt Cash Flow, Profitability, and Business Decisions
Growth can make bookkeeping mistakes more expensive. As a business adds customers, employees, vendors, payment methods, software, and financial accounts, the number of transactions increases and small errors can multiply quickly.
A missed invoice may delay cash collection. An incorrectly categorized expense may distort financial reports. Duplicate transactions can make costs appear higher than they are. Books that remain months behind can leave owners making important decisions without current financial information.
Accurate bookkeeping does not guarantee business success, but poor bookkeeping can create unnecessary costs, confusion, and risk. Understanding common mistakes can help growing businesses build stronger financial processes before problems become difficult to correct.
Why Bookkeeping Errors Matter More During Growth
A growing company typically has more moving parts than it did at an earlier stage. Financial decisions may involve hiring, marketing, equipment, financing, expansion, and new service lines.
When the underlying records are unreliable, management may misjudge profitability, available cash, customer balances, or upcoming obligations.
The financial cost of a bookkeeping mistake is not always a direct fee. It can also appear as wasted time, delayed collections, unnecessary spending, poor pricing decisions, or missed opportunities.
1. Falling Behind on the Books
One of the most common problems is allowing bookkeeping to fall several months behind. When records are outdated, financial reports cannot provide a current view of the business.
Delayed bookkeeping also makes errors harder to investigate because receipts, explanations, and transaction details may be more difficult to locate.
A regular weekly or monthly process is generally more manageable than a large cleanup at year-end.
2. Mixing Personal and Business Finances
Using the same bank account or credit card for both personal and business activity creates unnecessary complexity.
Mixed transactions can make expense categorization more difficult, reduce the usefulness of financial reports, and create additional work during tax preparation.
Dedicated business accounts and consistent recordkeeping help create a clearer financial trail.
3. Failing to Reconcile Bank Accounts
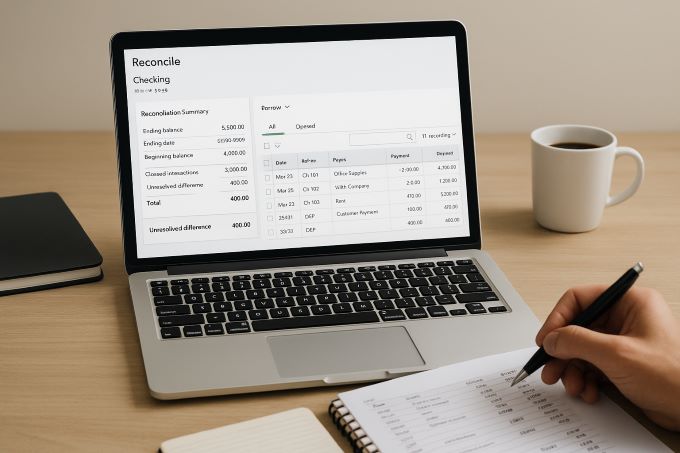
Bank reconciliation compares the bookkeeping records with the bank statement. Without reconciliation, missing transactions, duplicates, incorrect amounts, and other differences may remain undetected.
A bookkeeping system can appear organized while still containing significant errors if accounts have not been reconciled.
Regular reconciliation is one of the most important controls for maintaining reliable books.
4. Ignoring Credit Card Reconciliation
Business credit cards should be reconciled just like bank accounts. Automatic feeds can import transactions, but they do not guarantee accuracy.
Common problems include duplicated purchases, incorrectly recorded payments, missing credits, and charges assigned to the wrong category.
5. Recording Transfers as Income or Expenses
Moving money between business checking, savings, credit card, or other accounts is generally a transfer, not new revenue or a new operating expense.
If both sides of a transfer are categorized incorrectly, financial reports can overstate income or expenses.
Review transfers carefully, especially when several financial accounts are connected to bookkeeping software.
6. Duplicating Transactions
Duplicates often occur when a transaction is entered manually and then imported again through a bank feed or software integration.
They can also happen when payment processor deposits, invoices, and bank deposits are recorded separately without proper matching.
Duplicate expenses reduce reported profit, while duplicate income can make performance appear stronger than it actually is.
7. Misclassifying Expenses
Consistent categorization helps owners understand where money is going. When similar expenses are placed in different categories each month, reports become harder to compare.
Misclassification may also create additional cleanup work for accountants and tax professionals.
A clear chart of accounts and documented categorization rules can improve consistency.
8. Using Too Many Expense Categories
More detail is not always better. A chart of accounts with excessive categories can make bookkeeping difficult to maintain and financial reports harder to read.
Categories should be detailed enough to support useful decisions without creating unnecessary complexity.
9. Leaving Transactions Uncategorized
Uncategorized transactions should not accumulate month after month. Each unresolved item reduces confidence in the financial reports.
Create a process for identifying unclear charges and asking the appropriate person for supporting information while the transaction is still recent.
10. Failing to Save Receipts and Documentation
Receipts, invoices, contracts, statements, and other records can help explain transactions and support accounting or tax work.
Searching for documentation months later wastes time and may leave important transactions unsupported.
A consistent digital filing system can make retrieval much easier.
11. Not Tracking Accounts Receivable
A business can make sales without collecting the cash. If invoices are not tracked consistently, overdue balances may be forgotten.
Growing receivables can create cash flow pressure even when reported revenue looks strong.
Review an accounts receivable aging report regularly and follow up according to the company’s collection process.
12. Sending Invoices Late
If invoices are not sent promptly, the payment cycle starts late. Delays of a few days on every invoice can accumulate into meaningful cash flow problems.
Create a consistent invoicing schedule and make responsibilities clear so completed work is billed without unnecessary delay.
13. Applying Customer Payments Incorrectly
A payment recorded against the wrong invoice can make one customer appear overdue while another invoice appears paid.
Regular receivable review can identify misapplied payments before they create customer confusion or inaccurate collection activity.
14. Ignoring Accounts Payable
Unrecorded or poorly tracked vendor bills can create unexpected cash demands, late fees, or damaged vendor relationships.
A business should understand what it owes and when those obligations are due, even if payment will occur later.
15. Paying Bills Twice
Duplicate vendor payments can happen when invoices arrive through multiple channels or when responsibilities are unclear.
An organized accounts payable process should identify invoice numbers, payment status, and approvals before money is released.
16. Relying Only on the Bank Balance
A bank balance does not show the complete financial position of the business. It may not reflect unpaid customer invoices, upcoming payroll, credit card balances, vendor bills, taxes, loan obligations, or checks that have not cleared.
Use financial reports and cash flow planning alongside bank balances.
17. Confusing Profit With Cash Flow
A company can report a profit while experiencing a cash shortage. Revenue may have been earned but not collected, or cash may have been used for debt payments, equipment, inventory, or owner withdrawals.
Owners should review both profitability and cash movement when evaluating financial health.
18. Recording Loan Proceeds as Revenue
Borrowed money increases cash, but it is generally not ordinary operating revenue. Incorrectly categorizing loan proceeds can significantly distort the profit and loss statement.
Loan activity should be recorded according to appropriate accounting treatment, including principal and interest components of payments.
19. Recording an Entire Loan Payment as an Expense
Loan payments may include principal and interest. Treating the entire payment as a routine expense can distort both the profit and loss statement and balance sheet.
Review loan statements and obtain professional guidance when necessary.
20. Mishandling Large Equipment Purchases
Large purchases such as vehicles, machinery, computers, or equipment may require treatment different from routine operating expenses.
Flag significant purchases and retain documentation so an accounting or tax professional can determine the appropriate treatment.
21. Ignoring Payroll Liabilities
Payroll involves more than the amount employees receive. Depending on the business and jurisdiction, payroll records can include taxes, withholdings, benefits, and other liabilities.
Payroll transactions should be reconciled with payroll reports and bank activity. Businesses should rely on qualified professionals for applicable payroll requirements.
22. Poor Contractor Recordkeeping
Businesses that work with independent contractors should maintain accurate payment records and collect required information in a timely manner.
Waiting until year-end to organize contractor records can create unnecessary administrative pressure.
Worker classification and reporting requirements can be complex, so professional guidance may be appropriate.
23. Ignoring Sales Tax Responsibilities
When a business is required to collect sales tax, those amounts should not simply be treated as ordinary revenue.
Businesses should maintain records of taxable sales, tax collected, and related liabilities according to applicable requirements.
Sales tax rules vary by jurisdiction and transaction type.
24. Not Reviewing Financial Statements
Bookkeeping is not complete simply because transactions have been entered. Owners should review the resulting financial reports.
At minimum, many businesses benefit from reviewing:
- Profit and loss statement.
- Balance sheet.
- Accounts receivable aging.
- Accounts payable information.
- Cash flow or cash summary.
- Budget comparisons when applicable.
25. Failing to Investigate Unusual Changes
A sudden increase in an expense category, decline in margin, or large change in receivables deserves attention.
Financial reports are most useful when they lead to questions and action. Unusual changes may reflect legitimate business activity, bookkeeping errors, or emerging financial problems.
26. Using Outdated Financial Reports for Decisions
A report from three months ago may not reflect the company’s current financial capacity.
Growing businesses often make decisions quickly. Current books make it easier to evaluate hiring, marketing, purchasing, and expansion using recent information.
27. Failing to Track Recurring Expenses
Software subscriptions, memberships, service contracts, and other recurring costs can accumulate gradually.
Review recurring expenses periodically to identify duplicate tools, unused services, or plans that no longer provide enough value.
28. Not Monitoring Gross Margin
Revenue can increase while margins decline. Rising labor, materials, merchant fees, or fulfillment costs may reduce the amount the business retains from each sale.
Where applicable, accurate bookkeeping can help management monitor cost of goods sold or direct service costs and evaluate gross margin trends.
29. Making Pricing Decisions Without Cost Data
Pricing should reflect the economics of providing the service or product. If owners do not understand labor, materials, overhead, merchant fees, and other costs, prices may not support desired margins.
Reliable bookkeeping provides historical cost information that can support better pricing analysis.
30. Not Comparing Actual Results With a Budget
A budget creates a financial plan. Bookkeeping shows what actually happened.
Comparing the two can reveal overspending, revenue shortfalls, unexpected cost increases, or areas where performance exceeded expectations.
Without accurate books, budget comparisons lose much of their value.
31. Failing to Monitor Cash Reserves
Growth can consume cash. New employees, equipment, inventory, advertising, and expansion may require spending before additional revenue arrives.
Tracking available cash and upcoming obligations helps management understand how much flexibility the business has.
32. Growing Without Updating the Bookkeeping Process
A bookkeeping workflow designed for a business with a few transactions may not work when the company has hundreds or thousands.
As the business grows, it may need more frequent bookkeeping, clearer approvals, stronger documentation, better software integrations, or professional support.
33. Over-Automating Without Review
Automation can save time, but rules and integrations can make mistakes repeatedly.
A misconfigured bank rule may categorize dozens of transactions incorrectly. An integration may duplicate sales or deposits.
Automation should reduce manual work while preserving human review and reconciliation.
34. Sharing Accounting Logins
Shared passwords reduce accountability and can create security risks.
When software supports individual users, assign separate accounts and appropriate permissions. Remove access promptly when employees or outside professionals no longer require it.
35. Ignoring Data Security
Bookkeeping systems contain sensitive financial information. Weak passwords, unnecessary user access, and poor backup practices can expose the business to avoidable risk.
Use secure passwords, multi-factor authentication where available, appropriate access controls, and reliable backup procedures.
36. Waiting Until Tax Season to Clean Everything Up
Year-end cleanup can be expensive and stressful when an entire year of transactions needs to be reviewed at once.
Monthly bookkeeping spreads the work across the year and gives owners more useful information for managing the business in real time.
37. Assuming Bookkeeping and Tax Planning Are the Same
Accurate bookkeeping provides the records that tax professionals use, but routine bookkeeping does not automatically provide tax strategy or tax advice.
Businesses should understand the scope of each professional relationship and seek qualified advice when tax decisions are required.
38. Failing to Coordinate With the Accountant
Bookkeepers and accountants often work with the same financial information from different perspectives.
Clear communication can help resolve questions about account structure, unusual transactions, year-end adjustments, fixed assets, loans, and other matters before they create confusion.
39. Not Documenting Bookkeeping Procedures
When bookkeeping knowledge exists only in one person’s memory, the business becomes vulnerable to interruptions.
Document recurring processes such as invoicing, bill entry, reconciliations, receipt collection, payroll posting, month-end review, and financial reporting.
Written procedures also make it easier to train staff and maintain consistency.
40. Treating Bookkeeping as Data Entry Only
Accurate data entry is essential, but the greater value comes from turning financial records into useful information.
Business owners should use the books to understand profitability, cash flow, customer collections, spending trends, and financial capacity.
Bookkeeping becomes more valuable when it supports decisions rather than simply recording the past.
How Bookkeeping Mistakes Can Cost a Business Money
The cost of poor bookkeeping can appear in several ways:
- Late fees and penalties.
- Duplicate payments.
- Uncollected customer invoices.
- Unnecessary subscriptions.
- Incorrect purchasing decisions.
- Poor pricing decisions.
- Higher professional cleanup costs.
- Lost owner and staff time.
- Cash shortages caused by poor planning.
- Decisions based on inaccurate profitability.
- Difficulty preparing reliable information for financing or professional advisors.
Not every bookkeeping mistake creates a direct financial loss, but recurring errors can weaken the quality of decisions across the business.
A Better Bookkeeping Routine for Growing Businesses
- Update the books consistently.
- Use separate business financial accounts.
- Reconcile bank and credit card accounts monthly.
- Review accounts receivable and payable.
- Resolve uncategorized transactions promptly.
- Maintain supporting documents.
- Review payroll and financing activity.
- Check financial statements for unusual changes.
- Compare actual results with budgets.
- Monitor cash flow and margins.
- Review automation rules and integrations.
- Protect financial system access.
- Coordinate with accounting and tax professionals.
- Update bookkeeping procedures as the company grows.
Frequently Asked Questions
What is the most common bookkeeping mistake?
Falling behind is one of the most common problems because it contributes to many others. When bookkeeping is delayed, reconciliations, collections, expense review, and financial reporting also become less reliable.
Can bookkeeping mistakes affect cash flow?
Yes. Late invoicing, poor receivable tracking, duplicate payments, and failure to plan for upcoming bills can all contribute to cash flow problems.
How often should a growing business reconcile its accounts?
Many businesses reconcile active bank and credit card accounts monthly. Businesses with high transaction volume may require more frequent review. The appropriate schedule depends on the company’s needs and systems.
Can bookkeeping software prevent mistakes?
Software can reduce manual work and provide useful controls, but it cannot eliminate errors. Incorrect rules, duplicate integrations, missing information, and poor categorization can still produce inaccurate books.
When should a business consider professional bookkeeping help?
Professional support may be useful when the books are consistently behind, accounts are not reconciled, owners cannot rely on financial reports, transaction volume has increased significantly, or bookkeeping takes too much time away from operations.
How can a business tell whether its books are accurate?
Reconciled accounts, resolved transaction questions, consistent categorization, and financial reports that align with actual business activity are important indicators. Periodic review by qualified professionals may provide additional assurance depending on the business’s needs.
Protect Growth With Better Financial Records
As a business grows, bookkeeping mistakes can become more expensive because more decisions depend on accurate financial information.
A consistent process helps owners identify problems earlier, collect money faster, control expenses, understand profitability, and prepare for future growth with greater confidence.
Maikai Bookkeeping Services helps growing businesses maintain organized, timely financial records and dependable bookkeeping processes so owners can spend less time correcting financial data and more time building the business.